VAT Deadlines 2026 and 2027 in Germany for the Self-Employed, UG and GmbH
All VAT return dates for 2026 and 2027 as tables: monthly or quarterly filing under the €9,000 and €2,000 thresholds, the permanent deadline extension with its application and special advance payment, the grace period, late-filing surcharges, and filing with Norman without an ELSTER certificate.
- Category
- Taxes
- Updated
- Author
- Diana Chebotareva
The German advance VAT return (Umsatzsteuervoranmeldung / UStVA) is always due on the 10th of the following month, or on the 10th after the quarter ends for quarterly filers. If the 10th falls on a weekend or public holiday, the next working day applies. The next dates for monthly filers are 10 November 2026, 10 December 2026 and 11 January 2027; quarterly filers submit Q4 by 11 January 2027. Whether you file monthly or quarterly depends on your previous year's VAT liability. You can file in Norman without driving ELSTER yourself.
The essentials at a glance
- The UStVA is always due by the 10th day of the following month, for both monthly and quarterly filers. The next dates: 10 Nov 2026, 10 Dec 2026 and 11 Jan 2027.
- If the 10th is a Saturday, Sunday or public holiday, the deadline moves to the next working day (§ 108(3) of the German Fiscal Code). In 2027 this affects 12 April, 12 July and 11 October.
- Thresholds 2026 and 2027: more than €9,000 of prior-year VAT → monthly, €2,000–€9,000 → quarterly, up to €2,000 → the tax office can exempt you from advance returns.
- The permanent deadline extension pushes both the filing and the payment back by exactly one month. Apply for 2027 via ELSTER: monthly filers by 10 February 2027, quarterly filers by 12 April 2027.
- Only monthly filers make a special advance payment of 1/11 of the previous year's advance payments. It is offset against the December return.
- The 3-day grace period applies only to the payment by bank transfer, never to filing on time.
The tax deadline calculator lists every date for your case, with the permanent extension, EC sales list and payroll tax, and saves them to your calendar.
When is the VAT return due in 2026 and 2027?
The UStVA deadline always ends on the 10th day after the reporting period, the 10th of the following month (monthly filing) or the 10th after the quarter ends (quarterly filing). What counts is the electronic receipt at the tax office via ELSTER; paper submissions are not accepted. And the deadline shows: in our after-hours bookkeeping analysis, about 13% of all advance returns go out on the 10th, more than on any other day of the month. The base is more than 400 returns from over 100 businesses that keep their books digitally in Norman (mid-2024 to June 2026).
If the 10th falls on a Saturday, Sunday or public holiday, the deadline shifts to the next working day (§ 108(3) AO). Several dates in 2026 and 2027 are affected, the tables below already show the shifted dates. Watch out for regional public holidays at your tax office's location, too: they can push individual dates back even further.
VAT return deadlines 2026 at a glance
Monthly filing
| Reporting period | Standard deadline | With extension |
|---|---|---|
| January 2026 | 10 Feb 2026 | 10 Mar 2026 |
| February 2026 | 10 Mar 2026 | 10 Apr 2026 |
| March 2026 | 10 Apr 2026 | 11 May 2026* |
| April 2026 | 11 May 2026* | 10 Jun 2026 |
| May 2026 | 10 Jun 2026 | 10 Jul 2026 |
| June 2026 | 10 Jul 2026 | 10 Aug 2026 |
| July 2026 | 10 Aug 2026 | 10 Sep 2026 |
| August 2026 | 10 Sep 2026 | 12 Oct 2026* |
| September 2026 | 12 Oct 2026* | 10 Nov 2026 |
| October 2026 | 10 Nov 2026 | 10 Dec 2026 |
| November 2026 | 10 Dec 2026 | 11 Jan 2027* |
| December 2026 | 11 Jan 2027* | 10 Feb 2027 |
Quarterly filing
| Reporting period | Standard deadline | With extension |
|---|---|---|
| Q1 2026 (Jan–Mar) | 10 Apr 2026 | 11 May 2026* |
| Q2 2026 (Apr–Jun) | 10 Jul 2026 | 10 Aug 2026 |
| Q3 2026 (Jul–Sep) | 12 Oct 2026* | 10 Nov 2026 |
| Q4 2026 (Oct–Dec) | 11 Jan 2027* | 10 Feb 2027 |
* Deadline moved because the 10th falls on a weekend (§ 108(3) AO).
A week before the standard deadline and on the due date, Norman reminds you by email, with your VAT payable and whatever is still open. Norman calculates the return from your bank transactions and files it in one click: VAT return with Norman.
VAT return deadlines 2027
Three due dates in 2027 fall on a weekend and move to the Monday: 10 April, 10 July and 10 October. No national or regional public holiday falls on a 10th in 2027.
Monthly filing
| Reporting period | Standard deadline | With extension |
|---|---|---|
| January 2027 | 10 Feb 2027 | 10 Mar 2027 |
| February 2027 | 10 Mar 2027 | 12 Apr 2027* |
| March 2027 | 12 Apr 2027* | 10 May 2027 |
| April 2027 | 10 May 2027 | 10 Jun 2027 |
| May 2027 | 10 Jun 2027 | 12 Jul 2027* |
| June 2027 | 12 Jul 2027* | 10 Aug 2027 |
| July 2027 | 10 Aug 2027 | 10 Sep 2027 |
| August 2027 | 10 Sep 2027 | 11 Oct 2027* |
| September 2027 | 11 Oct 2027* | 10 Nov 2027 |
| October 2027 | 10 Nov 2027 | 10 Dec 2027 |
| November 2027 | 10 Dec 2027 | 10 Jan 2028 |
| December 2027 | 10 Jan 2028 | 10 Feb 2028 |
Quarterly filing
| Reporting period | Standard deadline | With extension |
|---|---|---|
| Q1 2027 (Jan–Mar) | 12 Apr 2027* | 10 May 2027 |
| Q2 2027 (Apr–Jun) | 12 Jul 2027* | 10 Aug 2027 |
| Q3 2027 (Jul–Sep) | 11 Oct 2027* | 10 Nov 2027 |
| Q4 2027 (Oct–Dec) | 10 Jan 2028 | 10 Feb 2028 |
* Deadline moved because the 10th falls on a weekend (§ 108(3) AO).
Thresholds 2026 and 2027: monthly, quarterly or annually?
How often you file depends on your previous year's VAT liability, the VAT collected minus the input VAT you paid to the tax office last year:
| Previous year's VAT liability | Filing frequency 2026 and 2027 |
|---|---|
| more than €9,000 | monthly |
| €2,000 to €9,000 | quarterly |
| up to €2,000 | the tax office can exempt you: then only the VAT annual return, no advance returns |
These thresholds have applied since 1 January 2025: the monthly threshold was raised from €7,500 to €9,000 (Bureaucracy Relief Act IV), and the exemption threshold from €1,000 to €2,000 (Growth Opportunities Act). Many older guides still quote the old figures, so check carefully which rhythm applies to you. The tax office usually reclassifies you once a year; for 2027 your 2026 liability counts. The exemption up to €2,000 is discretionary (§ 18(2) sentence 3 UStG): until the tax office exempts you, you file quarterly.
Small businesses under the Kleinunternehmer rule (§ 19 UStG) are exempt from the UStVA as long as they use the scheme, the deadlines above do not apply to them.
And new businesses? A stubborn myth persists here: the former obligation to file monthly for the first two years has been suspended for 2021 to 2026. For 2026 you are classified like everyone else, based on your expected VAT in the founding year (estimated and reported to the tax office), so usually quarterly, unless you exceed the €9,000 threshold. From 2027, as the law stands today, § 18(2) sentence 4 UStG applies again: if you start in 2027, you file monthly in the founding year and the following year, unless the legislature extends the suspension.
The starter book for your self-employment
Free e-book: registration, accounting, your first invoice, and taxes, plus a tax calendar, deductions cheat sheet, and invoice template.
Permanent deadline extension: one month more time
If the regular deadlines are too tight, you can apply for a permanent deadline extension (Dauerfristverlängerung). It pushes both filing and payment back by exactly one month, so 10 February becomes 10 March. The rules are in §§ 46 to 48 of the VAT Implementation Ordinance (UStDV). "Permanent" means the extension runs until you cancel it or the tax office revokes it, so you do not reapply every year. The tax office can revoke it if the tax claim appears at risk, for example after repeated late filing (§ 46 sentence 2 UStDV). It does not apply to the annual VAT return.

Any business that files advance VAT returns can apply, whatever its legal form: freelancers, sole traders, partnerships such as a GbR, OHG or KG, and a GmbH or UG. It works for monthly and quarterly filing. Monthly filers gain the most, because their time pressure is highest.
The special advance payment: calculating the 1/11
Only monthly filers make a special advance payment (Sondervorauszahlung) for the extension (§ 47 UStDV): one eleventh (1/11) of the sum of the previous year's VAT advance payments. It is due every year by 10 February and is offset against the December return, which with the extension is due on 10 February of the following year. If your December liability is too small, the tax office refunds the rest. So the payment is not an extra cost, it is an interest-free advance to the tax office.
Example: if your VAT advance payments in 2026 totalled €13,200, the special advance payment for 2027 is €13,200 ÷ 11 = €1,200. You pay this by 10 Feb 2027 and have it credited back via the December 2027 UStVA.
Quarterly filers make no special advance payment. They apply once, and the extension then keeps running.
How to apply via ELSTER
You apply electronically only, through ELSTER or connected accounting software. The official form is USt 1 H ("Antrag auf Dauerfristverlängerung / Anmeldung der Sondervorauszahlung").
- Log in to Mein ELSTER.
- Select "Formulare & Leistungen" (forms and services).
- Under Umsatzsteuer (VAT), open the form USt 1 H.
- Check your tax number and state whether you file monthly or quarterly.
- As a monthly filer, enter the sum of last year's advance payments. ELSTER calculates the 1/11 for you.
- Submit the application and transfer the special advance payment by the deadline.
You do not need to give a reason. The tax office normally grants the extension tacitly. You only hear from it if it refuses.
When to apply
The application must reach the tax office by the day on which the first return you want to move would be due:
| Filing | Apply by (2026) | Apply by (2027) | Applies from |
|---|---|---|---|
| monthly | 10 Feb 2026 | 10 Feb 2027 | January return |
| quarterly | 10 Apr 2026 | 12 Apr 2027* | Q1 return |
* 10 April 2027 is a Saturday, so the deadline moves to the Monday.
If you apply later, the extension only applies from the next reporting period. A monthly filer who missed 10 February can, for example, use it from the February return if the application arrives by 10 March.
When the extension pays off, and when it does not
It pays off if your bookkeeping is regularly under time pressure, holidays or sick leave put on-time filing at risk, or you want to keep the VAT due in the business for an extra month. It often gets tight: in our analysis, about one return in five arrives only in the last 48 hours before its due date. If you are often close to the deadline, the extension also cuts the risk of late-filing and late-payment penalties.
It is less attractive if you are permanently in an input VAT surplus and regularly receive refunds: the special advance payment then ties up money that you only get back with the December return. If you already close early and automatically, you rarely need the buffer.
Payment and grace period: when must the VAT reach the tax office?
The payment is due on the same day as the filing. The easiest route is a SEPA direct debit mandate: the tax office then collects the amount automatically and on time, so you can't miss a payment date.
On top of that there is a payment grace period of three days (§ 240(3) AO): if the payment reaches the tax office by the 13th, no late-payment surcharge applies. Two things to keep in mind:
- The grace period applies only to the payment, not to filing. The return itself must be submitted by the 10th.
- It does not apply to cash or cheque payments, only to bank transfers and direct debits.
I've always kept a separate VAT account for every business I've run. No complicated calculations, I just move 19% of every incoming payment into an interest-bearing account. It acts as both a VAT fund and an emergency pocket.
 Peter BoykoFounder of Norman
What happens if you miss the deadline?
If you file or pay late, two different surcharges can apply:
- Late-filing surcharge (for the late filing): for the UStVA this is at the tax office's discretion. It takes into account how long and how often you were late and the amount of tax, up to a maximum of €25,000 (§ 152(8) and (10) AO). The fixed calculation of 0.25% per month (minimum €25) that many guides cite applies to the annual return, not automatically to advance returns.
- Late-payment surcharge (for the late payment): 1% per started month on the outstanding tax amount, rounded down to €50 (§ 240 AO), after the grace period ends.
If you file no return at all, the tax office can estimate your turnover (usually to your disadvantage), send reminders and ultimately impose an enforcement penalty.
⚡️ Missed the deadline anyway? File the UStVA as soon as possible and pay immediately. For a first and short delay the tax office is often lenient, waiting it out only makes it more expensive.
How to file your VAT return on time with Norman
Norman's VAT return software calculates your return from your ongoing bookkeeping. This is how a filing runs:
- Connect your bank. Norman pulls in your transactions and matches receipts. The AI Bookkeeper assigns output VAT and input VAT to the boxes of the return. Connecting your bank is free.
- Get the reminder. A week before the deadline and on the due date at 10:00, Norman emails you your VAT payable and whatever is still open: bookings without a category, expenses without a receipt, an outdated bank connection.
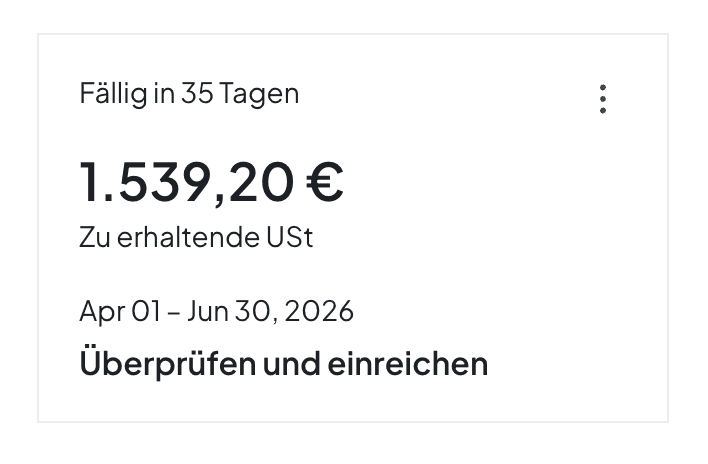
- Check the figures. Under Taxes, click Review and submit on the card for the period. Every line names the box in the official form, and the question mark opens the transactions behind it. For a UG or GmbH, an invoice counts in the month the service ends, even unpaid; for the self-employed, the payment date counts.
- Preview and submit. Preview and submit to Finanzamt shows the transmission protocol as a test case, exactly as the tax office receives it. With Submit to the Finanzamt, Norman transmits the return through the certified ELSTER interface. You need no ELSTER account of your own.
- Pay. With Pay now you transfer the amount due straight from your connected account to your tax office. If your tax office has a direct debit mandate, tick the SEPA direct debit box in the tax settings instead.
What it costs: connecting your bank and the preview are free. Filing starts at €9 a month for the self-employed and is included in the Max plan for UG and GmbH (€39 a month, with the EC Sales List, corporate and trade tax and the annual accounts), both billed yearly. More: file the VAT return without an ELSTER certificate.
Changelog
- October 2026: 2027 dates added, the 2026 and 2027 thresholds made precise (the tax office decides on the exemption up to €2,000), the 2027 extension with an example, figures on last-minute filing from our analysis, filing with Norman in five steps, and an FAQ.
Frequently asked questions
- When is the German VAT return due?
- By the 10th of the following month, or by the 10th after the quarter ends for quarterly filers. If the 10th falls on a weekend or public holiday, the next working day applies. The next dates are 10 Nov 2026, 10 Dec 2026 and 11 Jan 2027.
- Which thresholds apply to the VAT return in 2026 and 2027?
- If last year's VAT was more than €9,000, you file monthly; up to €9,000, quarterly. Up to €2,000, the tax office can exempt you from advance returns, and the annual return is enough. For 2027 the tax of 2026 counts (§ 18(2) UStG).
- By when do I apply for the permanent extension for 2027?
- Monthly filers submit form USt 1 H by 10 Feb 2027 and pay the 1/11 special advance payment by then. Quarterly filers apply by 12 Apr 2027, because 10 April is a Saturday. Once granted, the extension keeps running; you do not reapply.
- Does the grace period also apply to filing the VAT return?
- No. The three-day grace period under § 240(3) AO applies only to payment by bank transfer. The return itself must be transmitted on the due date, or the tax office can impose a late-filing surcharge.
- Do I have to file a nil return if I had no sales?
- Yes. A VAT return is due even with no turnover, as a nil return. If you skip it, the tax office can estimate your figures and add surcharges.
- Do new businesses have to file monthly?
- Not for 2021 to 2026: if you start in 2026, you are classified by the expected VAT of the founding year, usually quarterly. From 2027, as the law stands today, new businesses file monthly again in the founding year and the following year (§ 18(2) sentence 4 UStG), unless the legislature extends the suspension.
Never miss a VAT return deadline, no ELSTER certificate needed
Norman calculates your VAT return automatically from bank transactions and receipts, reminds you a week before the deadline and on the due date, and files it in one click through the certified ELSTER interface, no ELSTER account of your own needed. Filing starts at €9 a month for the self-employed and comes with the Max plan for UG and GmbH at €39 a month, billed yearly.