
Germany Tax Calendar 2027 and 2026: Every Tax Filing Deadline for GmbHs, UGs and the Self-Employed
Every German tax filing deadline for 2027 and the rest of 2026: UStVA, ZM, prepayments, trade tax and annual returns for GmbHs, UGs and the self-employed. With every shifted date (11 January, 18 May, 2 August 2027), the filing extension, surcharges and the return of monthly VAT filing for founders.
- Category
- Taxes
- Updated
- Author
- Diana Chebotareva
The next German tax deadlines are 10 December 2026 (November VAT return, income and corporation tax prepayment), 31 December 2026 (publication of the 2025 annual accounts) and 11 January 2027 (December and Q4 VAT return). In 2027, four VAT return dates, two ZM dates and two trade tax dates shift, and the 2026 annual returns are due on 2 August 2027 if you file without a tax adviser.
The calendar applies to GmbHs, UGs, traders and freelancers whose financial year is the calendar year. All dates are already moved to the next working day after weekends and nationwide public holidays (§ 108(3) AO).
Key facts
- VAT return (UStVA): the 10th of the following month. In 2027 moved to 11 January, 12 April, 12 July and 11 October.
- Prepayments: income and corporation tax on 10 March, June, September and December, trade tax in 2027 on 15 February, 18 May, 16 August and 15 November.
- 2026 annual returns: by 2 August 2027 without a tax adviser, by 29 February 2028 with one.
- New in 2027: under current law, founders file the UStVA monthly again in their founding year and the year after.
- Surcharges: paying late costs 1 % a month (Säumniszuschlag), filing late at least 25 € a month (Verspätungszuschlag).
The next deadlines: December 2026 to March 2027
| Date | Deadline | Who |
|---|---|---|
| Thu, 10 December 2026 | November UStVA · income and corporation tax prepayment Q4 | everyone liable for VAT · self-employed, GmbH, UG |
| Thu, 31 December 2026 | Publication of the 2025 annual accounts | GmbH, UG |
| Mon, 11 January 2027 | December 2026 and Q4 2026 UStVA | monthly and quarterly filers |
| Mon, 25 January 2027 | ZM Q4 2026 | EU B2B sellers |
| Wed, 10 February 2027 | January UStVA · filing extension and special prepayment | monthly filers |
| Mon, 15 February 2027 | Trade tax prepayment Q1 | traders, GmbH, UG |
| Wed, 10 March 2027 | February UStVA · income and corporation tax prepayment Q1 | everyone liable for VAT · self-employed, GmbH, UG |
If you have a permanent filing extension in 2026, your November return is due on 11 January 2027 and your December return on 10 February 2027.
2027 Germany tax calendar at a glance
| Month | Date | Deadline |
|---|---|---|
| January | Mon, 11 | UStVA December/Q4 2026 |
| January | Mon, 25 | ZM Q4 2026 |
| February | Wed, 10 | UStVA January · filing extension + special prepayment (monthly filers) |
| February | Mon, 15 | Trade tax prepayment Q1 |
| March | Wed, 10 | UStVA February · income and corporation tax prepayment Q1 |
| April | Mon, 12 | UStVA Q1/March · filing extension (quarterly filers) |
| April | Mon, 26 | ZM Q1 |
| May | Mon, 10 | UStVA April |
| May | Tue, 18 | Trade tax prepayment Q2 (after Whit Monday) |
| June | Thu, 10 | UStVA May · income and corporation tax prepayment Q2 |
| July | Mon, 12 | UStVA Q2/June |
| July | Mon, 26 | ZM Q2 |
| August | Mon, 2 | Income tax, EÜR, annual VAT, trade and corporation tax returns 2026 (without an adviser) |
| August | Tue, 10 | UStVA July |
| August | Mon, 16 | Trade tax prepayment Q3 |
| September | Fri, 10 | UStVA August · income and corporation tax prepayment Q3 |
| October | Mon, 11 | UStVA Q3/September |
| October | Mon, 25 | ZM Q3 |
| November | Wed, 10 | UStVA October |
| November | Mon, 15 | Trade tax prepayment Q4 |
| December | Fri, 10 | UStVA November · income and corporation tax prepayment Q4 |
| December | Fri, 31 | Publication of the 2026 annual accounts (GmbH, UG) |
What shifts in 2027
In 2027, four VAT return dates and two ZM dates fall on a weekend, and Whitsun moves one trade tax date:
| Deadline | Regular 2027 | Actual deadline | Reason |
|---|---|---|---|
| UStVA December 2026 / Q4 2026 | 10 January (Sun) | 11 January 2027 | weekend |
| UStVA March / Q1 2027 | 10 April (Sat) | 12 April 2027 | weekend |
| UStVA June / Q2 2027 | 10 July (Sat) | 12 July 2027 | weekend |
| UStVA September / Q3 2027 | 10 October (Sun) | 11 October 2027 | weekend |
| ZM Q1 2027 | 25 April (Sun) | 26 April 2027 | weekend |
| ZM Q2 2027 | 25 July (Sun) | 26 July 2027 | weekend |
| Trade tax Q2 | 15 May (Sat) | 18 May 2027 | weekend + Whit Monday (17 May) |
| Trade tax Q3 | 15 August (Sun) | 16 August 2027 | weekend |
| 2026 annual returns | 31 July (Sat) | 2 August 2027 | weekend |
The May date is the one people miss: 15 May 2027 is a Saturday and the Monday after is Whit Monday, so the trade tax prepayment is due on Tuesday, 18 May 2027. Corpus Christi on 27 May 2027 is a holiday only in parts of Germany.
Founders file monthly again in 2027. The monthly rule for new businesses was suspended for 2021 to 2026 (§ 18(2) sentence 6 UStG). From 2027, under current law, § 18(2) sentence 4 UStG applies again: in the founding year and the year after, you file the UStVA every month. Found a GmbH or UG in 2027 and that is 12 returns a year instead of 4.
Income tax: the annual return and prepayments
Without a tax adviser, your income tax return must reach the tax office by the end of July. With an adviser or a Lohnsteuerhilfeverein, you have until the end of February of the year after next:
| Tax year | without an adviser | with an adviser |
|---|---|---|
| 2025 | 31 July 2026 | 1 March 2027 (28 February is a Sunday) |
| 2026 | 2 August 2027 (31 July is a Saturday) | 29 February 2028 (2028 is a leap year) |
If you are self-employed, filing is mandatory even with a loss. The return includes the Anlage EÜR and, if you run a trade, the trade tax return. Every deadline with special cases is in the guide German tax return deadlines 2026 and 2027.
If you owed at least 400 € of income tax in the previous year, the tax office sets quarterly prepayments on 10 March, June, September and December. None of these falls on a weekend in 2026 or 2027. If your profit drops, apply to lower them, as described in estimated tax payments in Germany.
VAT return (UStVA) 2026 and 2027
The UStVA is due on the 10th of the following month, counted by when it reaches the tax office through ELSTER. Your previous year's VAT sets the rhythm (§ 18(2) UStG):
| VAT in the previous year | Filing rhythm |
|---|---|
| over 9,000 € | monthly |
| 2,000 to 9,000 € | quarterly |
| up to 2,000 € | the tax office may exempt you, then only the annual return |
| founding year and the year after (from 2027) | monthly |
| Kleinunternehmer | no UStVA |
Monthly filers (without the filing extension):
| Period | Deadline 2026 | Deadline 2027 |
|---|---|---|
| December of the previous year | 12 January 2026 | 11 January 2027 |
| January | 10 February 2026 | 10 February 2027 |
| February | 10 March 2026 | 10 March 2027 |
| March | 10 April 2026 | 12 April 2027 |
| April | 11 May 2026 | 10 May 2027 |
| May | 10 June 2026 | 10 June 2027 |
| June | 10 July 2026 | 12 July 2027 |
| July | 10 August 2026 | 10 August 2027 |
| August | 10 September 2026 | 10 September 2027 |
| September | 12 October 2026 | 11 October 2027 |
| October | 10 November 2026 | 10 November 2027 |
| November | 10 December 2026 | 10 December 2027 |
Quarterly filers (without the filing extension):
| Quarter | Deadline 2026 | Deadline 2027 |
|---|---|---|
| Q4 of the previous year | 12 January 2026 | 11 January 2027 |
| Q1 | 10 April 2026 | 12 April 2027 |
| Q2 | 10 July 2026 | 12 July 2027 |
| Q3 | 12 October 2026 | 11 October 2027 |
The grace period, rhythm and penalties in detail are in the guide VAT deadlines in Germany. The fastest way to file is VAT return software that submits straight to the Finanzamt.
Permanent filing extension (Dauerfristverlängerung): one extra month
With a Dauerfristverlängerung, the tax office moves every UStVA deadline back by one month: the 10th of the following month becomes the 10th of the month after. You apply through ELSTER and it runs until you cancel it. Monthly filers declare and pay a special prepayment (Sondervorauszahlung) every year.
| Monthly filers | Quarterly filers | |
|---|---|---|
| Application or special prepayment by | 10 February 2026 · 10 February 2027 | 10 April 2026 · 12 April 2027 |
| Special prepayment | yes, 1/11 of the previous year's prepayments | no |
| Shift | +1 month | +1 month |
Worked example: A GmbH filing monthly paid 33,000 € of VAT prepayments in 2026. For 2027 it declares a special prepayment of 33,000 € / 11 = 3,000 € by 10 February 2027. In return, its January 2027 UStVA is due on 10 March. The tax office credits the 3,000 € against the December 2027 UStVA, due with the extension on 10 February 2028. The money is not lost; it sits with the tax office interest-free for a year.
EC sales list (ZM) for EU business
If you sell to businesses in other EU countries, you file a Zusammenfassende Meldung with the Federal Central Tax Office by the 25th of the month after the quarter. The filing extension does not apply to the ZM.
| Period | Deadline 2026 | Deadline 2027 |
|---|---|---|
| Q4 of the previous year | 26 January 2026 | 25 January 2027 |
| Q1 | 27 April 2026 | 26 April 2027 |
| Q2 | 27 July 2026 | 26 July 2027 |
| Q3 | 26 October 2026 | 25 October 2027 |
If your intra-EU supplies of goods exceed 50,000 € in a quarter, you file monthly, by the 25th of the following month. What goes into the list is in the guide to the EC sales list in Germany.
Trade tax and corporation tax for GmbHs and UGs
GmbHs and UGs have the densest schedule, because corporation and trade tax prepayments come on top of the VAT returns:
| Obligation | 2026 | 2027 |
|---|---|---|
| Trade tax prepayment | 16 Feb · 15 May · 17 Aug · 16 Nov | 15 Feb · 18 May · 16 Aug · 15 Nov |
| Corporation tax prepayment | 10 Mar · 10 Jun · 10 Sep · 10 Dec | 10 Mar · 10 Jun · 10 Sep · 10 Dec |
| Annual accounts + corporation, trade and VAT returns (without an adviser) | 31 July 2026 for 2025 | 2 August 2027 for 2026 |
| Publication in the company register | 31 December 2026 for 2025 | 31 December 2027 for 2026 |
Publication is due 12 months after the end of the financial year. Micro companies may deposit instead of publish. How to check the prepayments is in GmbH tax prepayments, the annual return process in GmbH tax return.
Payroll tax and social security (if you employ people)
The payroll tax return (Lohnsteuer-Anmeldung) is due on the 10th of the following month, with the same shifts as the UStVA. Your previous year's payroll tax sets the rhythm (§ 41a(2) EStG):
| Payroll tax in the previous year | Filing rhythm |
|---|---|
| over 5,000 € | monthly |
| 1,080 to 5,000 € | quarterly |
| up to 1,080 € | annually |
Social security contributions are due earlier, on the third-to-last bank working day of the current month, and the contribution statement two working days before that. There is no grace period.
What a missed deadline costs
| For what? | Amount | |
|---|---|---|
| Verspätungszuschlag | filing late | 0.25 % of the assessed tax (less prepayments) per started month, at least 25 € (§ 152 AO) |
| Säumniszuschlag | paying late | 1 % per started month on the amount rounded down to 50 € (§ 240 AO) |
Payment example: Your December 2026 UStVA shows 4,180 € payable, due on 11 January 2027. If the transfer arrives by 14 January, the 3-day grace period applies. If it arrives on 15 January, you owe 1 % of 4,150 €, so 41.50 €, and again for every further started month.
Filing example: The 2025 income tax return was due on 31 July 2026. If it arrives on 15 March 2027, that is more than 14 months after the end of the tax year, so the surcharge becomes mandatory (§ 152(2) AO). With 4,000 € to pay, 0.25 % is only 10 € a month, so the minimum applies: 8 started months × 25 € = 200 €.
The grace period covers only bank transfer and direct debit, never the filing. If you need more time, apply for an extension through ELSTER before the deadline. How both surcharges are calculated is in the guide to late filing and late payment penalties.
The starter book for your self-employment
Free e-book: registration, accounting, your first invoice, and taxes, plus a tax calendar, deductions cheat sheet, and invoice template.
How to handle it with Norman
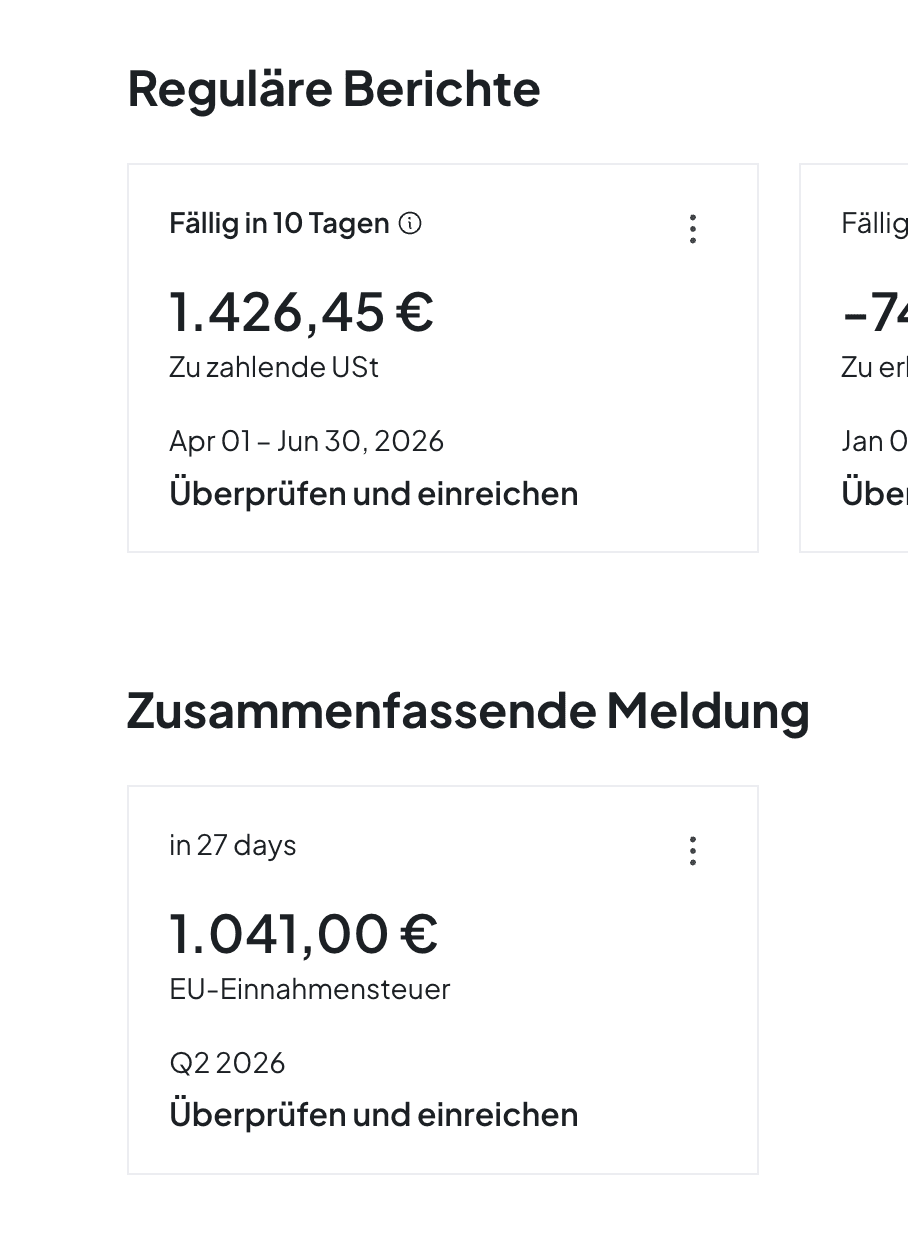
Most dates in this calendar are UStVA and ZM. Your AI Bookkeeper takes them over:
- Connect your bank. Norman pulls your transactions, matches receipts and books them with output and input VAT.
- Get the reminder. A week before every UStVA and ZM deadline, and on the day itself, Norman emails you your VAT payable or refund and everything still open. Shifted dates such as 11 January 2027 are already built in.
- Turn on the Tax Autopilot. Under "Taxes", Norman prepares the UStVA after each period and checks categories, receipts, duplicates and input VAT.
- Approve and submit. You open the preview, approve it, and Norman submits the UStVA to the Finanzamt through ELSTER, without your own ELSTER certificate. The card then shows "Submitted".
- Annual accounts and returns. For GmbHs and UGs, Norman prepares the annual accounts and E-Bilanz for the 2 August 2027 deadline. The self-employed submit their EÜR and income tax return straight from Norman.
GmbHs and UGs get this on the Max plan for 49 € a month, the self-employed on Max for 29 € a month, both billed yearly. A Steuerberater charges 200 to 800 € a month for ongoing bookkeeping. Everything about filing is on Norman VAT return software, the package for freelancers on taxes for the self-employed and for companies on taxes for GmbHs and UGs.
2026 Germany tax calendar: the current year
| Month | Date | Deadline |
|---|---|---|
| January | 12 | UStVA December/Q4 2025 |
| January | 26 | ZM Q4 2025 |
| February | 10 | UStVA January · filing extension + special prepayment (monthly filers) |
| February | 16 | Trade tax prepayment Q1 |
| March | 10 | UStVA February · income and corporation tax prepayment Q1 |
| April | 10 | UStVA Q1/March · filing extension (quarterly filers) |
| April | 27 | ZM Q1 |
| May | 11 | UStVA April |
| May | 15 | Trade tax prepayment Q2 |
| June | 10 | UStVA May · income and corporation tax prepayment Q2 |
| July | 10 | UStVA Q2/June |
| July | 27 | ZM Q2 |
| July | 31 | Income tax, EÜR, annual VAT, trade and corporation tax returns 2025 (without an adviser) |
| August | 10 | UStVA July |
| August | 17 | Trade tax prepayment Q3 |
| September | 10 | UStVA August · income and corporation tax prepayment Q3 |
| October | 12 | UStVA Q3/September |
| October | 26 | ZM Q3 |
| November | 10 | UStVA October |
| November | 16 | Trade tax prepayment Q4 |
| December | 10 | UStVA November · income and corporation tax prepayment Q4 |
| December | 31 | Publication of the 2025 annual accounts (GmbH, UG) |
Once you get into a cadence, the tax calendar becomes natural, and it sets up your accounting habit.
 Peter BoykoFounder of Norman
Changelog
- November 2026: New: 2027 first, the next deadlines to March 2027, monthly VAT filing for founders from 2027, worked examples for the special prepayment and the surcharges, the 2,000 € threshold clarified (the tax office may exempt you), deadline reminders and VAT filing with Norman, FAQ from real searches.
Frequently asked questions
- What is the deadline for tax filing in Germany for 2026?
- Your 2026 income tax return is due on 2 August 2027 if you file it yourself, because 31 July 2027 is a Saturday. With a tax adviser or a Lohnsteuerhilfeverein, the deadline is 29 February 2028. The 2025 return was due on 31 July 2026, or 1 March 2027 with an adviser.
- When is the German tax year?
- The German tax year is the calendar year, 1 January to 31 December. A GmbH or UG may choose a different financial year; then the annual return deadlines run from the end of that financial year.
- Which tax deadlines apply to a GmbH or UG in 2027?
- VAT returns on the 10th of the following month (moved to 11 January, 12 April, 12 July and 11 October 2027), corporation tax prepayments on 10 March, June, September and December, trade tax prepayments on 15 February, 18 May, 16 August and 15 November. Annual accounts with corporation, trade and VAT returns for 2026 by 2 August 2027 without an adviser, publication by 31 December 2027.
- Do founders file VAT returns monthly in 2027?
- Under current law, yes: the suspension of the monthly rule for new businesses only covers 2021 to 2026 (§ 18(2) sentence 6 UStG). From 2027, businesses file monthly in their founding year and the following year again, unless the legislator extends the suspension.
- What happens if the 10th falls on a weekend or public holiday?
- The deadline moves to the next working day (§ 108(3) AO). In May 2027 this pushes trade tax from Saturday the 15th past Whit Monday to Tuesday, 18 May. Regional holidays at the seat of your tax office can push single dates further.
- Does the 3-day grace period also cover filing?
- No. The grace period under § 240(3) AO only covers payment by bank transfer or direct debit. The return itself must reach the tax office on the deadline.
Stop tracking deadlines: Norman reminds you and files your VAT return
Your AI Bookkeeper calculates your VAT payable or refund from your bookings, reminds you a week before every UStVA and ZM deadline, and submits the return to the Finanzamt straight from Norman. The self-employed and GmbHs and UGs get it on the Max plan, GmbHs and UGs with annual accounts and E-Bilanz. A Steuerberater charges 200 to 800 € a month for ongoing bookkeeping.